
Impact of moving job to yearly personal income tax report (1721 A1)
Ready to Transform Your Payroll & HR Management?
Talk directly with our payroll & HR specialist — No commitment required.
On 20 February 2014, I shared my experience regarding the tax impact as result of moving to other company to Personal Income Tax Reporting. This time I will share another experience which related to move to other company and its implication to his/her yearly personal income tax report , if he/she receives net salary (company borne tax of employee)
Last month I helped an employee of my client who was late to submit yearly income tax report, because he confused that he should pay a significant amount up to Rp 19 million, because he move from jobs. These calculation is according to the tax regulation (PER 31/PJ/2012), which he/she resigned from first company, the first company recalculated his/her tax income from based on yearly income to his/her income up to his/her resignation. This will automatically make tax return which will be taken by the previous company, as he/she got net salary. This is happened again in the next company, the next company will calculate his salary based on his/her working period which is less than a year. When he/she joined both income from the previous and the current company, he/she should pay the tax difference.
Another example is a single not married obtained Rp 10 million net for 6 months, then he moved to other company and got Rp 11 million net. He hope that he got salary increasing, however if he combine his income, he should pay additional tax amounting Rp 7.1 million, because each company deducted his salary with a yearly amount of non taxable income (PTKP), so that his taxable income is less than Rp 50 million after non taxable income (Rp 24,3 million) for 6 months and the applicable tax tariff will be only 5%. However if he combine his yearly income, it will be more than Rp million and the applicable tax tariff will be up to 15%. This is the reason that he should pay additional tax up to Rp 7.1 million.
How to avoid this? I recommend he/she negotiates to the new company to bear this tax income implication, although the new company may not be agree. The easiest way is the person needs to provide his/her 1721 A1 from previous company to new company, so that the new company can take the amount of income and paid tax from previous company into tax income calculation. This way will minimize the tax difference at the end of the year.
Next time I will share what the pro and cons of net and gross salary for company and employees.
Related Articles
Explore more insights and updates from Widya Presisi Solusi
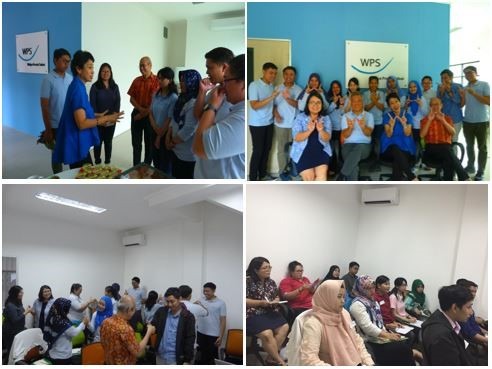
Softskill Training on 9th and 10th July in WPS New Second Office
On the 9th and 10th July 2019, we conducted a soft-skill internal training in order t...
BPJS Kesehatan - Indonesia National Health System
At the end of 2014 National Health Insurance (NHI) became hot topic for companies in...
Updated compensation and benefits based on Indonesian Regulations
Please open this linkhttp://www.expat.or.id/business/employee-compensationbenefits.ht...